
CVS Health Split: US Pharmacy Giant to Divide Into Two Companies in 2028
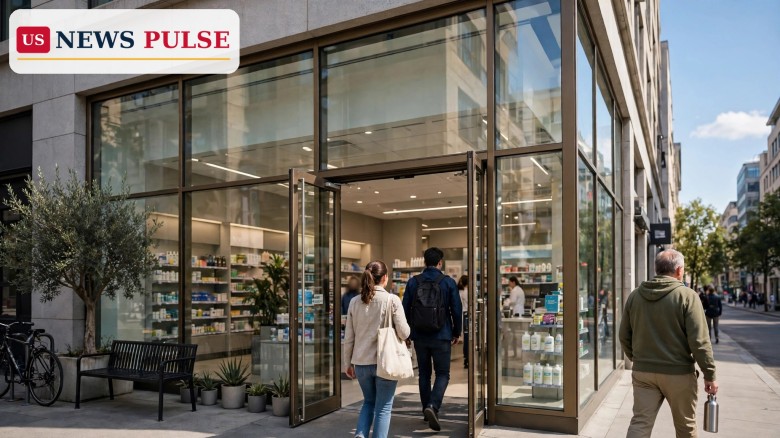
CVS Health will split into two independent, publicly traded companies, unwinding one of the largest vertical-integration experiments in American healthcare. The company announced the breakup on Wednesday, November 4, 2026, saying the separation will be a tax-free transaction expected to close in the first half of 2028. Shareholders will own shares in both new companies, each free to pursue a narrower strategy and raise capital on its own terms.
Key Points
- CVS Health announced on November 4, 2026, that it will split into two independent publicly traded companies.
- CVS Pharmacy will run about 9,000 retail pharmacies, mail-order pharmacy, specialty drugs, 800 MinuteClinics and the Health100 technology business.
- The provisionally named CVS Health will hold insurer Aetna, pharmacy benefit manager CVS Caremark, CVS Specialty, Oak Street Health and Signify Health.
- The tax-free separation is expected to close in the first half of 2028, and shareholders will own stock in both companies.
- CVS shares fell about 12 to 12.6 percent in midday trading to about $79.94, even as third-quarter revenue rose 5.4 percent to $108.4 billion.
What Happened
CVS unveiled the plan alongside its third-quarter results, framing the split as the next step after years of building a single company touching almost every part of American healthcare. The retail business will become a standalone company called CVS Pharmacy, with estimated 2026 revenue of about $145 billion, led by Prem Shah. It will house roughly 9,000 retail pharmacies, mail-order pharmacy, specialty drugs, about 800 MinuteClinics and the Health100 technology services business.
The second company, provisionally called CVS Health, will be led by current chairman and chief executive David Joyner. It will bring together insurer Aetna, pharmacy benefit manager CVS Caremark, CVS Specialty, Oak Street Health primary-care centres and Signify Health home-health evaluations. In effect, insurance and care delivery will sit in one company, while the shops and front-door pharmacy services most Americans walk into will sit in the other. CVS said the split will not close stores or change what patients pay for prescriptions, and no closures were announced.
Background and Context
The breakup reverses a strategy that shaped American healthcare for nearly twenty years. In 2007, CVS merged with Caremark, combining a huge retail pharmacy chain with a pharmacy benefit manager that negotiates drug prices and processes claims for employers and insurers. The logic was that owning both sides would cut costs and give CVS bargaining power with drug makers.
That logic was extended in 2018, when CVS completed its $69 billion acquisition of Aetna, one of America's largest health insurers. The combined company argued it could manage a patient's whole journey, from insurance card to clinic visit, prescription and home-health check. Rivals followed a similar path, but scale also brought complexity and competing demands: a retail business dependent on footfall and leases has different needs from an insurance business dependent on medical costs and premiums. Pharmacy benefit managers are also under intense political pressure over drug prices and rebates, with a new federal transparency rule set to force greater fee disclosure.
What the CVS Health Split Means for Patients and Shareholders
For patients, CVS says the practical experience should not change at first. Stores will stay open, MinuteClinics will keep operating, and prescription prices should not move because of the split alone. Over time, however, a standalone CVS Pharmacy will live or die on retail and pharmacy-services performance, giving it a clearer reason to invest in stores, staffing, clinics and digital services.
A standalone insurance and care company, meanwhile, can focus on Aetna membership, Caremark drug negotiations, Oak Street clinics and Signify home visits without also running a vast shop estate. Supporters argue that focus should bring better employer deals and clearer accountability when costs rise. For shareholders, the immediate reaction was negative: shares fell about 12 to 12.6 percent in midday trading to about $79.94. Breakups often trigger an initial sell-off before the market reassesses the parts, and CVS must publish detailed financials for each new company before investors can judge whether the parts are worth more than the whole.
Reactions and Market Response
The market's verdict was swift, and striking because it came on a day of otherwise strong results. Total third-quarter revenue rose 5.4 percent year over year to $108.4 billion, net profit was nearly $2.2 billion, against a $4 billion net loss in the third quarter of 2025, and CVS raised full-year earnings guidance. That the stock fell anyway underlines how much weight investors put on the breakup itself, including the cost of splitting systems, brands and contracts, and the possible loss of bargaining power from owning an insurer, a benefit manager and a pharmacy chain under one roof.
Why It Matters
The CVS split is a test of the vertical-integration model that has defined American healthcare for a generation. If the two companies thrive, rivals may face pressure to follow, and policymakers may conclude that sprawling healthcare conglomerates are not the best way to lower costs.
The decision also lands as drug prices, pharmacy access and insurance costs remain central political issues, with pharmacy closures in rural and low-income areas already drawing concern. Large American companies in other sectors have also been breaking up on the argument that focused firms are easier to run and value, making CVS the healthcare sector's biggest test of that argument. For more on the week's market moves, see our report on the Wall Street rally after Democrats took Congress, and on healthcare pressures, see our report on the Marathon Health data breach affecting 5.7 million people.
What Happens Next
CVS will now work through the detailed separation plan, including legal structure, debt distribution, tax treatment and the commercial agreements governing how the two companies work together after 2028. Investors will look for pro-forma statements showing how each business performed alone. Prem Shah must set out how CVS Pharmacy will grow retail, clinic and technology services, while David Joyner must explain how the insurance and care company will control medical costs and manage scrutiny of benefit managers. The timetable, in the first half of 2028, gives CVS time to prepare, but also leaves a long period in which rivals can poach staff and win contracts.
Frequently Asked Questions
When will the CVS Health split happen?
The separation is expected to close in the first half of 2028, as a tax-free transaction. Shareholders will own shares in both new companies.
What will the two new companies be?
CVS Pharmacy will run about 9,000 pharmacies, mail-order and specialty pharmacy, 800 MinuteClinics and Health100. The provisionally named CVS Health will hold Aetna, CVS Caremark, CVS Specialty, Oak Street Health and Signify Health.
Will CVS stores close because of the split?
CVS says the split will not close stores or change what patients pay for prescriptions.
Why did CVS shares fall after the announcement?
Shares fell about 12 to 12.6 percent in midday trading to about $79.94, despite stronger third-quarter results, suggesting investor caution about separation costs, disruption and value.
How strong were CVS's third-quarter results?
Revenue was $108.4 billion, up 5.4 percent year over year, with net profit of nearly $2.2 billion, against a $4 billion loss a year earlier. CVS also raised full-year earnings guidance.
© 2026 US News Pulse. All rights reserved.
 Print
 Save