
Nasdaq Crashes 5.3% as Chip Stocks Plunge, Wiping Out Post-Midterm Rally
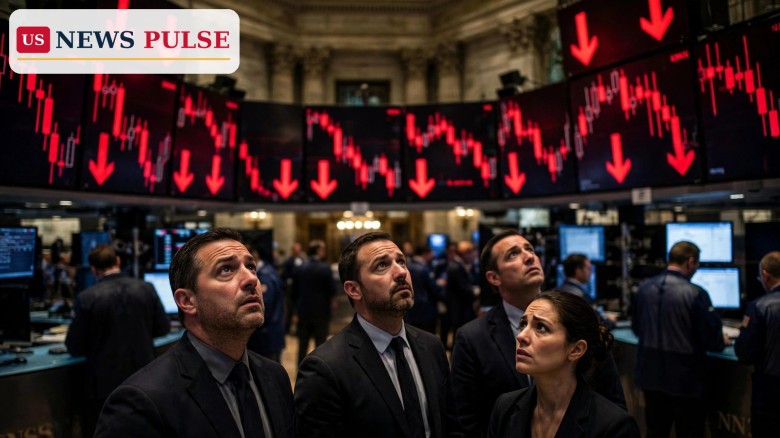
US stocks plunged on Thursday, November 5, 2026, wiping out the post-midterm rally in a single brutal session as chip stocks crashed and the Nasdaq Composite tumbled more than 5%. By mid-afternoon in New York, the Nasdaq was down 5.30%, the S&P 500 had lost about 3.3% to 3.5%, and the Dow was down roughly 1,300 points, or about 2.2%, in intraday trading. The sell-off reversed Wednesday’s euphoric rally in full as investors questioned whether the trillions being poured into artificial intelligence and data centres will ever pay off fast enough to justify today’s prices.
The Nasdaq crash was led by the semiconductor stocks that powered the market’s long climb. The PHLX Semiconductor Index fell as much as 11%, its worst day since March 2020. Nvidia dropped 8.27%, AMD plunged 15.62%, Micron sank 14.77% and SanDisk collapsed about 20%. Qualcomm fell roughly 9% to 10% after its smartphone chip sales missed estimates.
Key Points
- The Nasdaq Composite fell 5.30% by mid-afternoon on Thursday, November 5, 2026, the S&P 500 lost 3.3% to 3.5% and the Dow dropped about 1,300 points.
- The Nasdaq is now about 11% below its record closing high of 27,599.89 set on October 6, putting it on course to confirm a correction, a 10% pullback from a peak.
- The PHLX Semiconductor Index fell as much as 11%, its worst day since March 2020, with Nvidia down 8.27%, AMD down 15.62%, Micron down 14.77% and SanDisk down about 20%.
- Investors are reassessing the AI investment boom, questioning whether heavy spending on data centres and chips will pay off quickly enough.
- Bitcoin dropped below $76,000, down about 5% in 24 hours, as the flight from risk spread beyond stocks.
What Happened
The selling began early and gathered force through the morning. By 11:56 a.m. ET, the Nasdaq was already down 5.30%, a drop of that size in a single session is rare outside of a crisis. Chip stocks, software names and the big technology companies that dominate the index all fell together, while the Dow’s loss of roughly 1,300 points showed the damage was not confined to technology.
The trigger was not a single headline but a mood shift. For months, investors had treated every dollar of AI spending as a promise of future profit. On Thursday, they asked harder questions: how quickly will the giant data-centre buildout pay for itself, and what happens to chip demand if the biggest buyers slow down? The same doubts had already knocked markets on Election Day. Qualcomm’s earnings gave the doubts a concrete shape, as its smartphone chip sales missed estimates.
Background: From Record Highs to a Correction in a Month
Only a month ago, the mood could hardly have been more different. The Nasdaq closed at a record 27,599.89 on October 6, 2026, the high-water mark of a rally built on the belief that artificial intelligence would transform the economy. Since then, the index has fallen about 11%, a slide that began with worries about AI spending and accelerated as earnings season forced investors to look at the numbers behind the story.
The midterm elections added a political twist. On Tuesday, November 3, Democrats swept Congress, and markets first fell, then rallied hard on Wednesday as investors decided that divided government and the end of election uncertainty were good for stocks. The Dow’s 1,569-point jump was the best post-midterm rally since 1982. Thursday’s crash showed how fragile that relief was: the political questions were settled, but the economic ones were not.
Nasdaq Crash: Chip Stocks Lead the Rout
Semiconductors were the centre of the storm. The PHLX Semiconductor Index’s drop of as much as 11% was its worst since the pandemic crash of March 2020, after the sector had already slid 12% over three sessions. Thursday turned a steady retreat into a collapse.
Nvidia’s 8.27% fall was the most consequential move of the day. As the world’s largest company by market value and the supplier of the chips at the heart of the AI boom, Nvidia has become a proxy for the entire trade. AMD’s 15.62% plunge and Micron’s 14.77% drop showed the selling was about the sector’s future, not one company’s results.
Reactions
Across Wall Street, the tone on Thursday was one of abrupt reassessment rather than panic. Traders described a market looking for a reason to take profits after a long run to record highs and finding it in the growing doubts about AI spending. A rally that had carried the Dow more than 1,500 points higher on Wednesday was erased in a matter of hours.
Why It Matters
The Nasdaq crash matters because the AI trade has become the market. Technology and semiconductor stocks make up a huge share of the major indexes, and their rise has supported consumer spending and business confidence. A correction in those names can ripple through pension funds, retirement accounts and the broader economy.
It also matters politically. The Democrats’ sweep of Congress on November 3 has raised expectations of tighter scrutiny of data-centre expansion and of the big technology companies, and a sell-off gives those debates a sharper edge. If the AI buildout slows, the consequences would reach far beyond Wall Street. For ordinary investors, Thursday was a reminder of how quickly sentiment can reverse.
What Happens Next
All eyes now turn to Friday’s session and to the next round of earnings and economic data. If buyers step in, Thursday may be remembered as a sharp but healthy reset after a long rally. If the selling continues, the correction could deepen and spread to sectors so far spared.
Investors will also watch the chipmakers closely. Any fresh guidance from Nvidia, AMD or Micron about demand for AI chips could either calm the market or confirm its worst fears. For now, the market’s message is clear: the AI boom is no longer being taken on faith.
Frequently Asked Questions
How far did the Nasdaq fall on Thursday, November 5, 2026?
The Nasdaq Composite fell 5.30% by mid-afternoon in New York, the S&P 500 lost about 3.3% to 3.5% and the Dow dropped roughly 1,300 points, or about 2.2%, in intraday trading, with the market still open.
Is the Nasdaq in a correction?
The Nasdaq is now about 11% below its record closing high of 27,599.89 on October 6, 2026. A correction is a fall of 10% or more from a recent peak, so the index is on course to confirm one.
Why did chip stocks fall so sharply?
Investors are questioning whether heavy spending on AI data centres and chips will pay off quickly enough, and Qualcomm’s smartphone chip sales missed estimates. The PHLX Semiconductor Index fell as much as 11%.
Which stocks fell the most?
Among the big names, AMD dropped 15.62%, Micron fell 14.77%, Nvidia lost 8.27%, Qualcomm fell about 9% to 10%, and SanDisk sank about 20%. Bitcoin also fell below $76,000.
What happened the day before the crash?
On Wednesday, November 4, stocks rallied sharply after the midterms, with the Dow jumping 1,569 points and the S&P 500 rising 1.6%. Thursday’s sell-off wiped out that rally in a single session. Read our report on the Dow’s 1,569-point post-midterm rally and our coverage of the Election Day market slide.
© 2026 US News Pulse. All rights reserved.
 Print
 Save