US October Budget Deficit Hits Record $404 Billion as Fiscal 2027 Opens
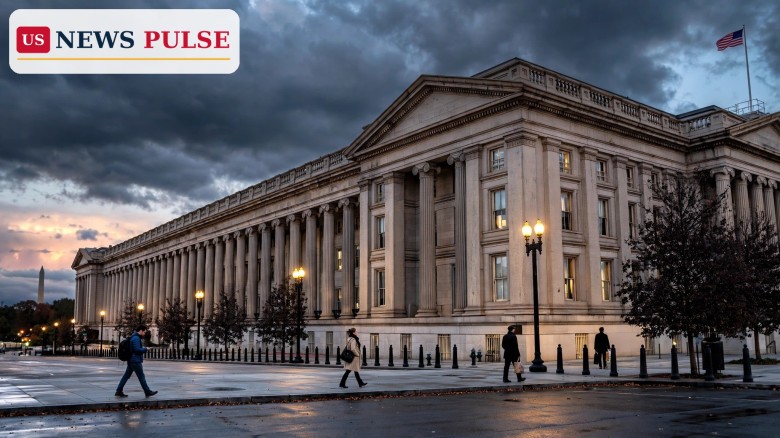
The United States opened fiscal year 2027 with a record October budget deficit of $404 billion, the Treasury Department said on Thursday, November 12, 2026, as tax receipts fell and federal spending surged — a gap $120 billion, or 42%, wider than the same month a year earlier.
Key Points
- The federal government ran a $404 billion deficit in October 2026, a record for the month and 42% higher than a year earlier.
- October receipts fell $35 billion, or 9%, to $369 billion, partly on lower net customs duty collections.
- Individual non-withheld taxes fell $29 billion, or 36%, largely a timing effect from delayed California filing deadlines after the 2025 wildfires.
- Reported October outlays hit a record $773 billion, up $84 billion, or 12%, driven by farm relief payments and a delayed military payment.
- Gross interest on the federal debt rose $11 billion, or 11%, to $115 billion in a single month.
What Happened
The Treasury Department released the October figures on Thursday, November 12, 2026, opening the books on fiscal year 2027, which began on October 1. The headline number — a $404 billion deficit in a single month — is the largest October shortfall on record, and it came from both sides of the ledger moving in the wrong direction at once: money coming in fell, and money going out rose sharply.
On the revenue side, receipts fell $35 billion, or 9%, to $369 billion, partly on lower net customs duty collections. On the spending side, outlays hit a record $773 billion, up $84 billion, or 12%. Agriculture Department spending rose $14 billion, or 80%, on farm relief payments, and military spending rose $28 billion, or 30%, including an October payment to military trust funds delayed by last year's government shutdown. After calendar adjustments for November benefit payments shifted into October, the adjusted deficit would have been $285 billion, up $94 billion, or 49%, from a year ago.
Background: How the Federal Budget Year Works
The federal fiscal year runs from October 1 to September 30, so October is the first month of fiscal 2027. The monthly Treasury statement is the most timely official scoreboard of the government's finances: receipts are what it takes in, outlays are what it spends, and the difference is the deficit when spending exceeds revenue. A single month rarely decides a fiscal year, but October sets the tone, and this one set it loudly.
October's numbers also carry the fingerprints of last year's disruption. The shutdown delayed a military trust-fund payment into this October, inflating the spending comparison, while delayed California filing deadlines inflated last October's tax take. Both effects are real money moving across months, not accounting fiction — yet the adjusted figure still shows a deficit up 49%, so the deterioration is not only a quirk of timing.
October Budget Deficit: What Drove the Record Gap
The October budget deficit was driven by weaker receipts and higher outlays. Farm relief payments pushed Agriculture Department spending up 80% in a single month, a reminder that support for farmers remains a large and lumpy part of federal spending. Military spending rose 30%, though part of that is the delayed trust-fund payment catching up after the shutdown rather than a new surge in defence activity.
The revenue side is the more closely watched half of the story. Net customs duty collections fell, a notable softening at a time when tariffs have been a central feature of trade policy. And while the $29 billion fall in individual non-withheld taxes is explained in large part by the California timing effect, the Treasury still took in materially less from individual taxpayers than a year ago. Receipts of $369 billion against outlays of $773 billion left a gap of more than two dollars of spending for every dollar taken in. Interest costs are the slow-burning part of the deficit: at $115 billion for October alone, gross interest on the federal debt is running at a pace that would exceed $1.3 trillion over a full year if sustained.
Reactions: The Numbers Land in a Fierce Fiscal Debate
The Treasury's monthly statement is a release of figures rather than a commentary, and the Reuters report of the numbers carried no quoted reaction from administration officials. The figures nevertheless land in the middle of a fierce debate in Washington over the federal budget, where both parties now have fresh numbers to argue with. For critics of current spending levels, a record October deficit is evidence that the government is spending too much too fast. For critics of the revenue side, the fall in receipts — including lower customs duties — is evidence that the tax and tariff mix is not bringing in enough.
Why It Matters
A deficit of this size in the first month of the fiscal year matters because it sets the trajectory for the twelve months that follow. If October's pace were sustained, the annual deficit would be far larger than the roughly $1.8 trillion-scale shortfalls of recent years. The more durable signal is the interest bill: $115 billion in a month is a cost that cannot be cut by a policy decision, and it grows as the debt grows. If receipts stay soft while outlays stay high, the deficit will widen further, and the government will have to borrow more — pushing interest costs higher still.
What Happens Next
The next test comes with the November figures, due in mid-December. They will show whether the California timing effect washes out of the receipts comparison and whether the farm relief and military payments were one-off bulges or the start of a higher spending plateau. If receipts recover and outlays settle, the October record may look like a distorted opening month. If they do not, the fiscal year will open with a deficit running well ahead of last year's pace, and the numbers will feed into the debate over spending bills in Congress.
Frequently Asked Questions
How big was the October budget deficit?
$404 billion, a record for October and $120 billion, or 42%, higher than the same month a year earlier, according to the Treasury Department.
Why did receipts fall?
October receipts fell $35 billion, or 9%, to $369 billion, partly on lower net customs duty collections, while individual non-withheld taxes fell $29 billion, or 36%, largely on delayed California filing deadlines.
Why did spending rise so much?
Outlays hit a record $773 billion, up 12%. Agriculture spending rose $14 billion, or 80%, on farm relief payments, and military spending rose $28 billion, or 30%, including a payment delayed by last year's shutdown.
What is the adjusted deficit?
After adjusting for November benefit payments shifted into October in both fiscal years, the deficit would have been $285 billion, up $94 billion, or 49%, from a year ago.
How much did the government pay in interest?
Gross interest on the federal debt rose $11 billion, or 11%, from the previous October to $115 billion in the month.
Related coverage: Wall Street closes mixed Monday as Dow rises and Nasdaq falls; Wall Street rally as Dow jumps 1,203 points; United Airlines bans AI agents from booking flights.
© 2026 US News Pulse. All rights reserved.
 Print
 Save